Retiring before 65 can open the door to a slower, more enjoyable Texas Hill Country lifestyle: but it also creates a healthcare gap that deserves attention.
For many early retirees, employer-sponsored coverage ends years before Medicare eligibility. A person retiring at 60 may need to arrange coverage for roughly five years. Someone leaving work at 55 may face a much longer bridge.
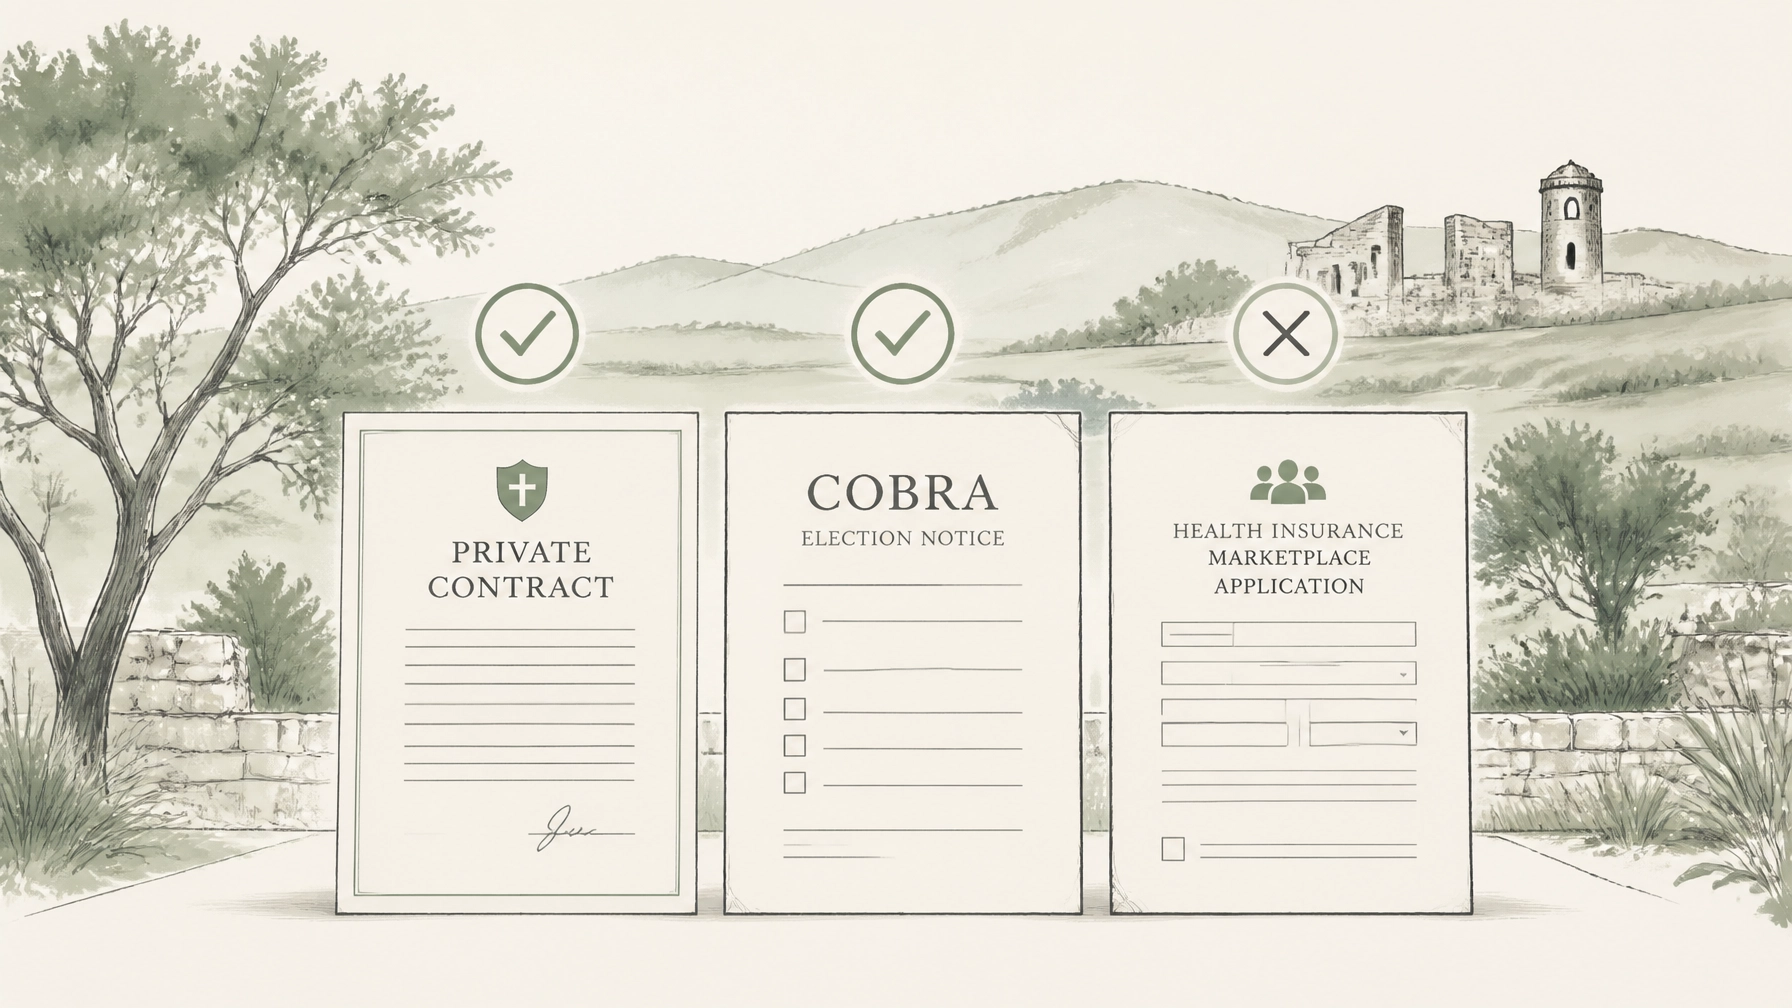
The three main options are:
- COBRA continuation coverage
- ACA Marketplace insurance through HealthCare.gov
- Private individual insurance purchased outside the Marketplace
Each option can serve a different purpose. The right choice depends on your expected income, current doctors, prescription needs, preferred hospitals, budget, and how long you need coverage.
“If you retire before you’re 65 and lose your job-based health plan when you do, you can use the Health Insurance Marketplace® to buy a plan.” : HealthCare.gov
The first question: How long is your healthcare bridge?
Before comparing plans, determine the length of the coverage gap.
- Retiring at 64 may require coverage for only a few months.
- Retiring at 62 may require a bridge of approximately three years.
- Retiring at 60 may require approximately five years.
- Retiring at 55 may require close to a decade of coverage before Medicare eligibility.
The longer the bridge, the more important it becomes to evaluate annual premium changes, deductibles, provider networks, prescription coverage, and the effect of healthcare costs on your broader retirement lifestyle.
Healthcare should be included in the retirement cash-flow discussion alongside housing, travel, dining, outdoor recreation, and other goals. A peaceful Hill Country retirement is easier to enjoy when a major medical expense does not arrive as an unexpected surprise.

Option 1: COBRA continuation coverage
COBRA allows eligible workers and family members to continue their former employer’s group health plan for a limited period after certain qualifying events, including job loss or a reduction in work hours.
Why retirees consider COBRA
The biggest advantage is continuity. COBRA generally preserves:
- Your existing doctors
- Your hospital system
- Your plan’s provider network
- Your prescription formulary
- Your deductible progress
- Your copay and coinsurance structure
- Your current plan design
That continuity can be particularly valuable if you are receiving ongoing treatment, managing a chronic condition, or approaching a planned procedure.
COBRA can also be convenient if you retire late in the year and need coverage for a relatively short period before Medicare begins.
The primary drawback: cost
Under federal rules, a plan may generally charge up to 102% of the total cost of coverage: the employee and employer portions combined, plus a potential 2% administrative fee. Your employer is no longer required to pay the share it contributed while you were working.
That means a plan that felt reasonably priced as an employee can become substantially more expensive after retirement.
COBRA coverage after job loss or reduced hours typically lasts up to 18 months, although certain circumstances may allow longer coverage periods. Read the official Department of Labor COBRA guidance and review your election notice carefully.
When COBRA may make sense
COBRA may be worth considering when:
- You need your existing doctors and hospitals.
- You have already paid toward a large annual deductible.
- You are in the middle of treatment.
- You need coverage for a short period.
- Your employer offers a temporary subsidy.
- The employer plan has benefits that are difficult to replace in your area.
COBRA should not be chosen solely because it is familiar. Compare its total annual cost with Marketplace alternatives before enrolling.
Option 2: ACA Marketplace coverage
Texas residents use the federal Marketplace at HealthCare.gov. ACA Marketplace plans are often the most important option for early retirees because eligibility and pricing can be based on household income rather than employment status.
Marketplace plans must provide essential health benefits and protect people with pre-existing conditions. According to HealthCare.gov, Marketplace plans include coverage categories such as hospitalization, emergency services, prescription drugs, laboratory services, mental health care, and preventive care.
The potential advantage: income-based savings
When you apply, HealthCare.gov estimates whether you qualify for:
- A premium tax credit that reduces the monthly premium
- Additional savings on deductibles, copayments, and coinsurance
- Medicaid or other public coverage programs, depending on eligibility
The premium tax credit is based on information such as estimated household income and family size. The HealthCare.gov premium tax credit explanation provides a general overview.
For early retirees, projected income may include more than wages. Withdrawals from traditional retirement accounts, pensions, interest, dividends, and other taxable income can affect the Marketplace calculation. Because income reporting can have tax consequences, do not treat a retirement withdrawal or Roth conversion as a healthcare-subsidy tactic without discussing it with an appropriately qualified tax professional.
In 2026, HealthCare.gov states that the temporary additional savings associated with the COVID pandemic ended on December 31, 2025. People who qualify for savings may therefore pay more than they did under the enhanced rules. Update your application with current income information rather than relying on a prior-year estimate.
The trade-off: network and cost-sharing design
ACA plans can be affordable on a monthly basis but may have:
- Narrower provider networks
- Higher deductibles
- Different hospital affiliations
- Separate prescription tiers
- Higher out-of-pocket costs before the plan pays substantially
The lowest premium is not necessarily the lowest-cost plan. A Bronze plan may have a smaller monthly premium but a larger deductible. A Silver or Gold plan may cost more each month while offering more predictable costs when you use healthcare services.
Review the summary of benefits, provider directory, drug list, deductible, coinsurance, copayments, and annual out-of-pocket maximum before selecting a plan.
Option 3: Private insurance outside the Marketplace
“Private insurance” can refer to several different products, so early retirees should ask exactly what is being offered.
ACA-compliant off-exchange plans
Some ACA-compliant individual plans are sold directly by insurance companies or through licensed agents rather than through HealthCare.gov. These plans generally follow ACA protections, including coverage for pre-existing conditions and essential health benefits.
The important drawback is that federal premium tax credits are available only through the Marketplace. If you buy an off-exchange plan, you generally pay the full premium.
An off-exchange plan may still be worth comparing when:
- Your income is above the subsidy eligibility range.
- You want a different network or plan design.
- Your preferred doctors are not available through the lowest-cost Marketplace options.
- You value a particular PPO structure.
Non-ACA-compliant policies
Some private policies, including certain short-term or medically underwritten products, may have lower initial premiums. However, they may also:
- Exclude pre-existing conditions
- Limit covered benefits
- Exclude certain services
- Impose benefit caps
- Use different renewal rules
- Provide less comprehensive protection than ACA plans
A lower premium can be misleading if the policy does not cover the care you are most likely to need.
For a multi-year bridge to Medicare, comprehensive coverage and predictable protection deserve more attention than the first monthly price you see.

Side-by-side comparison
| Consideration | COBRA | ACA Marketplace | Private insurance outside Marketplace |
|---|---|---|---|
| Main advantage | Keeps your former employer plan | Potential income-based savings and ACA protections | More plan-shopping flexibility |
| Premium structure | Up to 102% of total group-plan cost | Depends on plan, location, age, household, and estimated income | Usually full price; no Marketplace premium tax credit |
| Pre-existing conditions | Governed by the existing group plan | Protected under ACA rules | Protected if ACA-compliant; restrictions may apply to non-ACA plans |
| Provider network | Same employer network | Varies by plan; may be narrower | Varies by insurer and plan |
| Coverage duration | Usually limited, often 18 months after job loss | Can generally continue until Medicare if eligible and renewed | Depends on the policy and applicable rules |
| Best fit | Short-term continuity or ongoing treatment | Many moderate-income early retirees | Those seeking a specific plan or paying full price |
A practical decision process
1. Start with your doctors and prescriptions
List your preferred physicians, hospitals, specialists, medications, and pharmacies. A plan that excludes your primary hospital system may not be suitable, even if its premium is attractive.
2. Request the exact COBRA premium
Do not estimate. Ask the plan administrator for the full monthly premium, administrative fee, maximum duration, deductible status, and termination rules.
3. Estimate annual household income
Use a realistic estimate that includes retirement distributions and other relevant income. If your income changes during the year, update your Marketplace application promptly.
4. Compare total annual exposure
Look beyond the monthly premium. Compare:
- Annual premiums
- Deductible
- Copayments
- Coinsurance
- Prescription costs
- Out-of-pocket maximum
- Travel and out-of-network rules
5. Protect your enrollment timing
Losing job-based coverage generally creates a Special Enrollment Period. HealthCare.gov says you can generally apply from 60 days before through 60 days after the loss of coverage.
Be cautious about voluntarily ending COBRA. Outside Open Enrollment, voluntarily dropping COBRA generally does not create a new Special Enrollment Period. When COBRA coverage expires, however, you generally have 60 days to enroll in a Marketplace plan.
The HealthCare.gov Special Enrollment Period guidance explains the timing and documentation requirements.
The larger retirement-planning question
Healthcare coverage is not separate from retirement planning. The premium you pay, the income you recognize, and the amount you reserve for deductibles can influence how much flexibility you have for travel, home improvements, charitable giving, or a Hill Country lifestyle.
Mau Sanchez Capital provides fiduciary financial planning and investment management separately from Texas Retirement Journal, the educational publication. A properly designed retirement strategy can help you evaluate healthcare costs alongside portfolio withdrawals, liquidity needs, and long-term spending priorities. It should not replace enrollment guidance from HealthCare.gov, an insurance professional, or qualified medical and tax professionals.
For more lifestyle and wellness perspectives, read The Wellness Retirement: How Texas Hill Country Spas and Retreats Are Redefining Healthy Aging.
Final takeaway
For many Texas early retirees, the ACA Marketplace deserves a careful first look because it may provide comprehensive coverage with income-based savings. COBRA can be valuable when continuity of care matters or when Medicare is only a short distance away. Private coverage may provide useful alternatives, but the policy’s structure and exclusions must be understood before enrollment.
The best healthcare bridge is not automatically the cheapest premium. It is the coverage that fits your timeline, medical needs, preferred providers, retirement income, and ability to absorb out-of-pocket expenses.
Schedule a private meeting with a fiduciary financial advisor today by calling (512) 593-8380 or by visiting: https://calendly.com/portafoliocapital/15min
Portafolio Capital Management dba Mau Sanchez Capital is a Registered Investment Adviser. This content is for informational purposes only and does not constitute investment advice or a solicitation to buy or sell any security. Advisory services are provided only pursuant to a written advisory agreement.
To learn more about Texas retirement lifestyles and financial preparedness, explore the Texas Retirement Journal.
This article may include stories, scenarios, and perspectives created or assisted by artificial intelligence. Although the individuals and circumstances described may be fictional, the topics are intended to reflect real financial, personal, and lifestyle issues that retirees and individuals commonly face.
The content is provided to encourage readers to consider different perspectives that may affect their retirement, regardless of whether they are currently planning, approaching retirement, or already retired. It is intended for general educational and informational purposes only and should not be interpreted as personalized investment, financial, tax, legal, medical, or retirement-planning advice.
Individual circumstances vary. Readers should independently verify any information presented and consult appropriately qualified professionals before making financial or personal decisions. No advisory, professional, or client relationship is created through the use of this website.
Leave a Reply